What your insurer asks for after water damage
Water damage claims in Ventura County are settled on paper, not on the phone. From Oxnard to Ojai, SOS Restoration meters the walls, photographs every room and itemizes the loss. Your carrier reads evidence instead of guessing. Call (805) 427-9039 at any hour.

somebody who can dispatch, not a recording
water pulled, smoke cleared, rooms rebuilt
from the coast to the backcountry of Ventura County
IICRC #70194273
We run both halves of the job. First come extraction, drying and the removal of whatever the water ruined. Then come the framing, drywall, texture, paint, cabinets and floor that turn a gutted room back into a room.
The construction half is licensed, CSLB #1131134, and the mitigation half holds IICRC #70194273. The technician on site reads the meters and tells you what is genuinely wet. That visit is free, and nothing is owed if you send us home.
What follows is how the paperwork behaves in this county. It is not advice about your policy. Nobody here can tell you how yours lands.
My insurance company already picked a contractor for me. Do I have to use them?
No, and the rule underneath that phone call runs the opposite direction from how it usually gets presented.
California’s claims regulations say a carrier cannot recommend or suggest a building contractor unless two things happen in order. First, the person on the policy is told in writing that they may choose their own repair company.
Then that person asks for, or agrees to, the carrier’s. Written notice first. Your choice second. That is 10 CCR 2695.9.
So the name you were handed on the phone is a suggestion with a condition on it, not an assignment. Take it if you like. Hire the outfit your neighbor used instead, or us, and the file carries on the same.
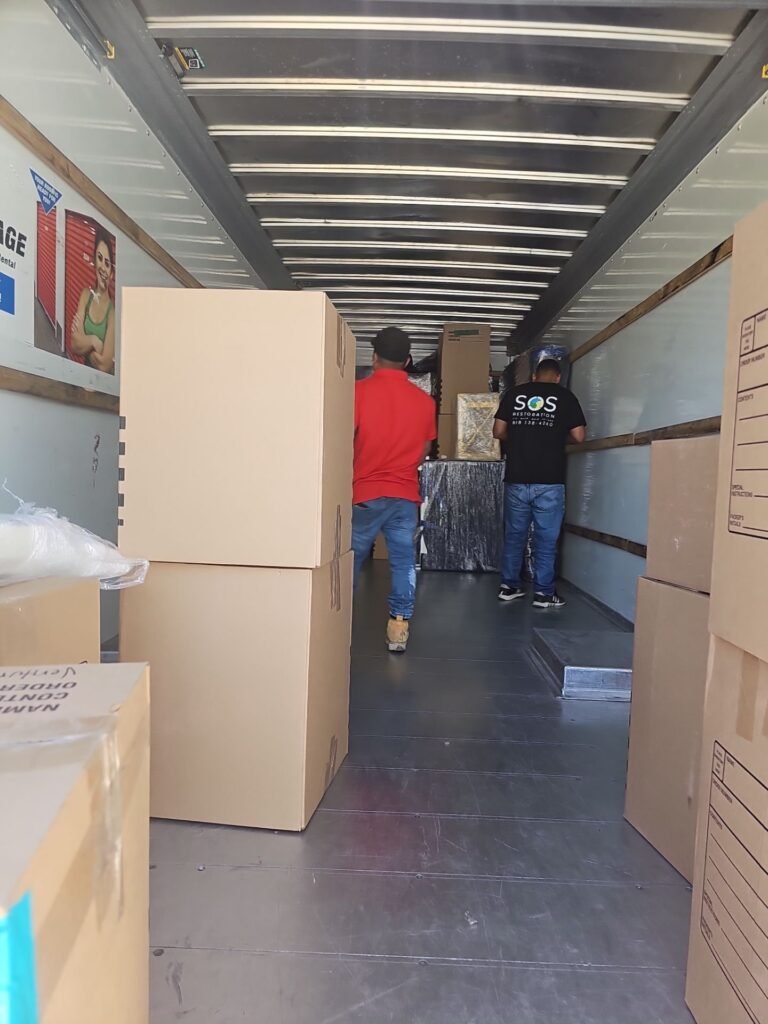
Read every restoration website in this county and you will not find that paragraph on any of them. The one local page that spells it out belongs to a public adjuster.
That adjuster is paid a percentage of whatever you collect. So there it is, from a contractor.
Keep the letter that offered you the choice. Ask the carrier’s adjuster to note which company you picked, and the date.

The water came out of the creek, not out of a pipe. Is that even the same claim?
Probably not, and this is the most expensive distinction on the page.
A standard homeowners form is built around water arriving suddenly and accidentally from inside the building. A supply line that lets go. A heater that splits. A fitting under a sink that quits while the house is asleep.
Water rising from outside and spreading over the ground is flood, and flood is a separate federal policy.
The trap here is who believes they are out of range. Ventura County has 1,331 paid federal flood claims on its record. Of those, 535, just over 40 percent, were written on properties rated outside the high-risk mapping.
Nationally that share is around one in five. Here it is two in five. In the ZIP codes of the city of Ventura it is three in five: 250 of 419. Oxnard’s ZIP codes run the same way, 65 of 98.
Two clocks make it harsher. A new flood policy generally takes 30 days to take effect. Buying one the week a storm hits the forecast buys nothing for that storm.
And of the 7,333 homes mapped inside the county’s high-risk zone, only 2,264 carry the coverage.


It is also worth knowing which map your city is being judged on. Santa Paula, Fillmore, Camarillo and the unincorporated county were remapped in 2024. Moorpark and Simi Valley are still measured against maps drawn in 2010.
Cannot tell which side of the line your loss falls on? We wrote a separate piece on flood claim or water damage claim.
Mud came off the burn scar and into the house. Which policy is that?
Mudflow sits on the flood policy. A slope that simply gave way sits on neither.
The whole difference is whether the material was flowing or the hillside failed underneath itself. That single word decides whether anyone pays.
Which is why the photographs you take before the shovels arrive outweigh anything you say later. Shoot the debris where it stopped, the line it left on the wall, the yard, the street it came down. A photograph can argue movement. A memory cannot.


Federal paperwork already files fire and mud here as one event, four separate times. The Thomas Fire declaration ran from December 4, 2017 through January 31, 2018.
The older ones in 1993, 2003 and 2007 each stretched into the following spring for the same reason. The risk stays high until vegetation grows back, up to 5 years.
Our storm damage crews work the same phone number. There is more in what the first winter after a fire does.
How long can the carrier take before it answers me?
Three numbers, and they are not suggestions.
Your carrier has 15 calendar days to acknowledge that you reported a loss. It has another 15 to reply to any letter or message from you that reasonably calls for a reply.
And once it has your proof of claim in hand, it has no more than 40 calendar days. In that time it must accept or deny in writing, with the reasons written out.
Put those dates in a notebook the day it happens, and date every email. Ask for answers on paper. A pleasant phone call leaves nothing behind for anyone to read six weeks later.

How long do I have to rebuild before the rest of the money goes away?
Twelve months normally, and no less than three years when the governor has declared an emergency over it.
Counting begins the day the first check clears. That check pays the secondhand value of what was ruined, depreciated for its age. The balance shows up only once the work is genuinely finished.
If the loss ties back to a declared emergency, the law keeps that window open at least 36 months. Good cause adds further 6-month extensions.
Good cause looks like drawings stuck at the plan review desk, or materials on back order. It also looks like no crews left because half the county is rebuilding. Insurance Code 2051.5.
This matters in Ventura County more than most places, because declared emergencies keep arriving. The county has drawn 17 presidential disaster declarations for flooding or severe storms between 1965 and 2024.
The two most recent came in 2023 and 2024. A homeowner who assumed twelve months and rushed the work often had three years and did not know it.

Who pays for somewhere to live while the house is torn open?
Your own policy does, out of the part that pays for living somewhere else while the house is unusable.
That heading is called loss of use. The money is not coming out of anyone’s pocket at the job. In a declared emergency the floor is 24 months of those expenses, counted from the start of the loss.
It can stretch by another 12, so 36 altogether, where the homeowner is acting in good faith. The delay also has to be outside their control.
Where the only obstacle is a civil authority order keeping people out, the floor drops to two weeks. It gets extended two weeks at a time. Insurance Code 2060.
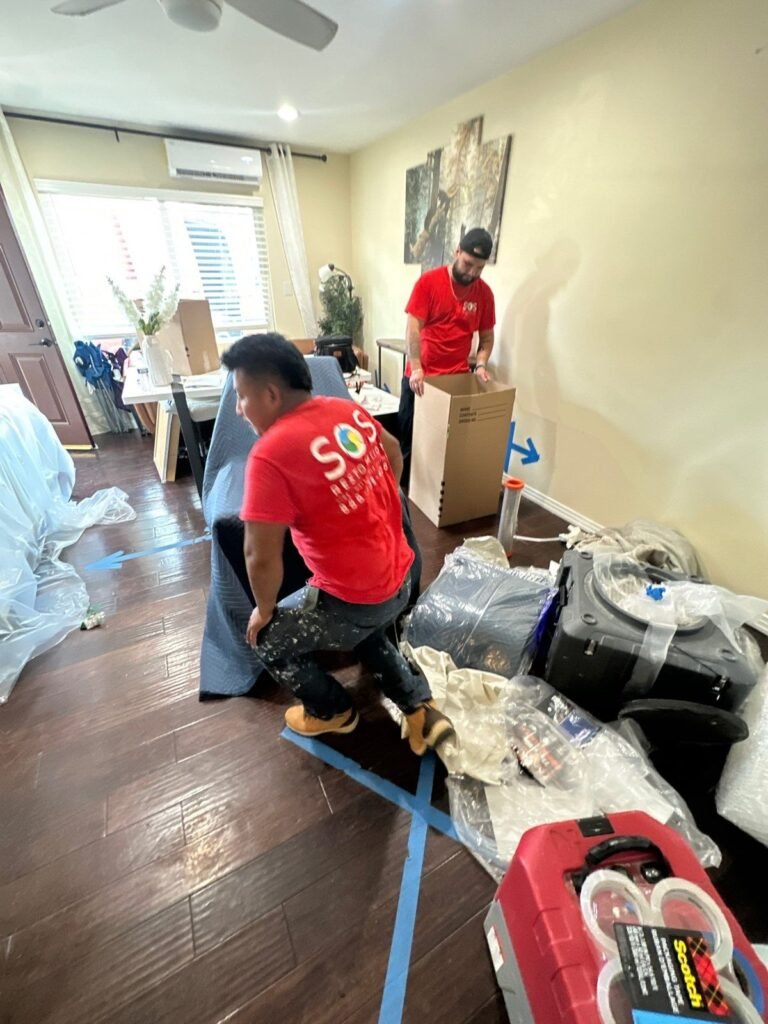
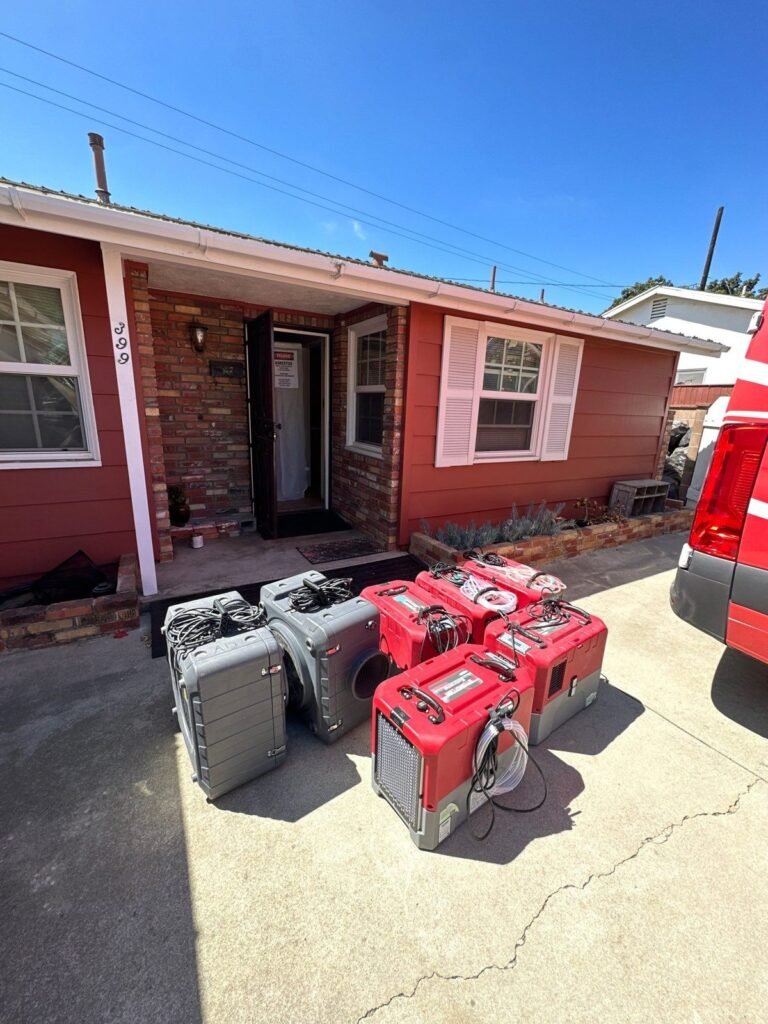
One more piece of it almost nobody claims. On a total loss in a declared emergency, the carrier has to render an advance payment.
It covers no less than four months of living expenses, and it comes when the policyholder asks. It has to be asked for. Nobody volunteers it.
What exactly do you write down, and what does the carrier do with it?
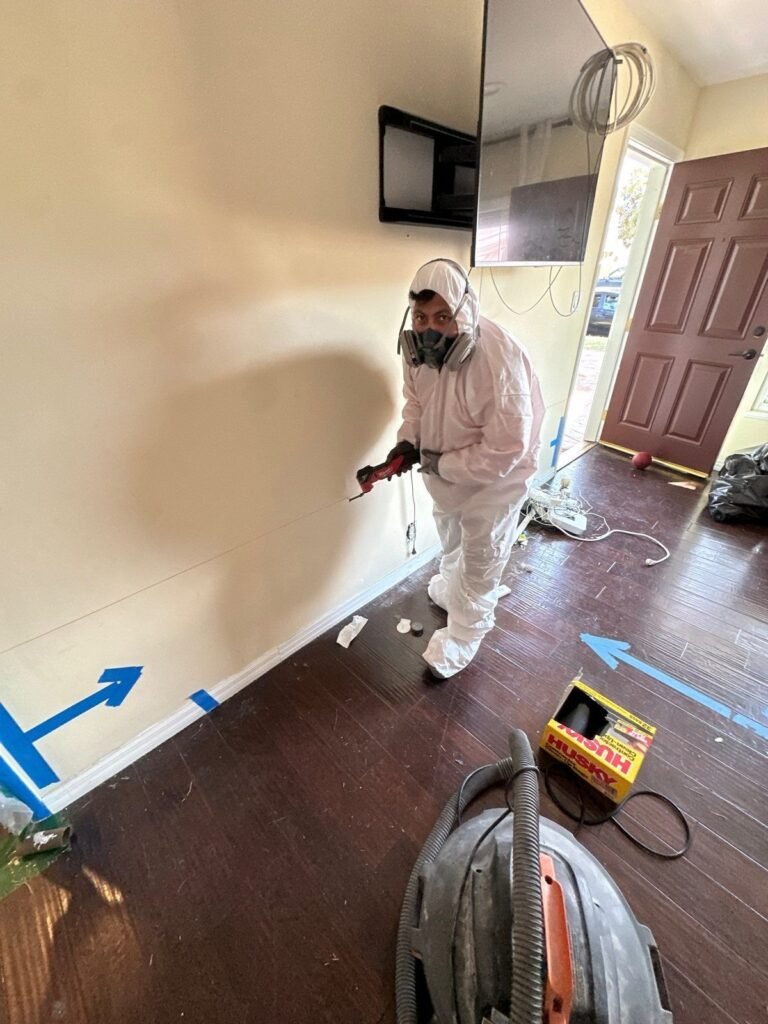
Readings, photographs and a line-by-line list of the work, every page of it dated.
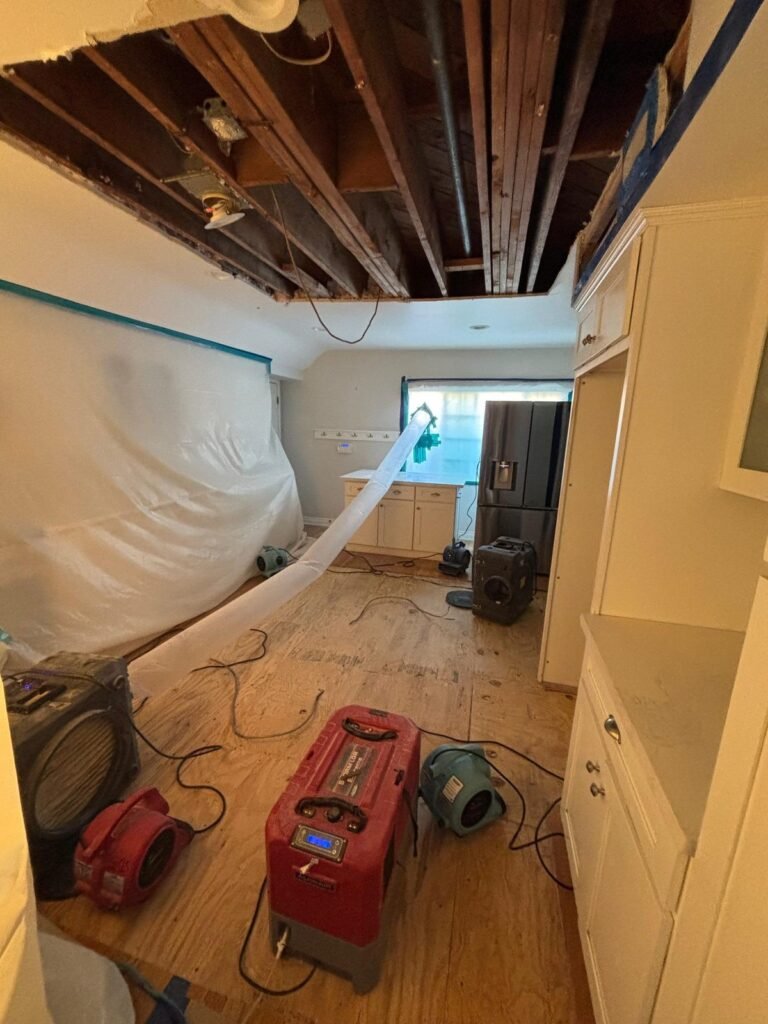
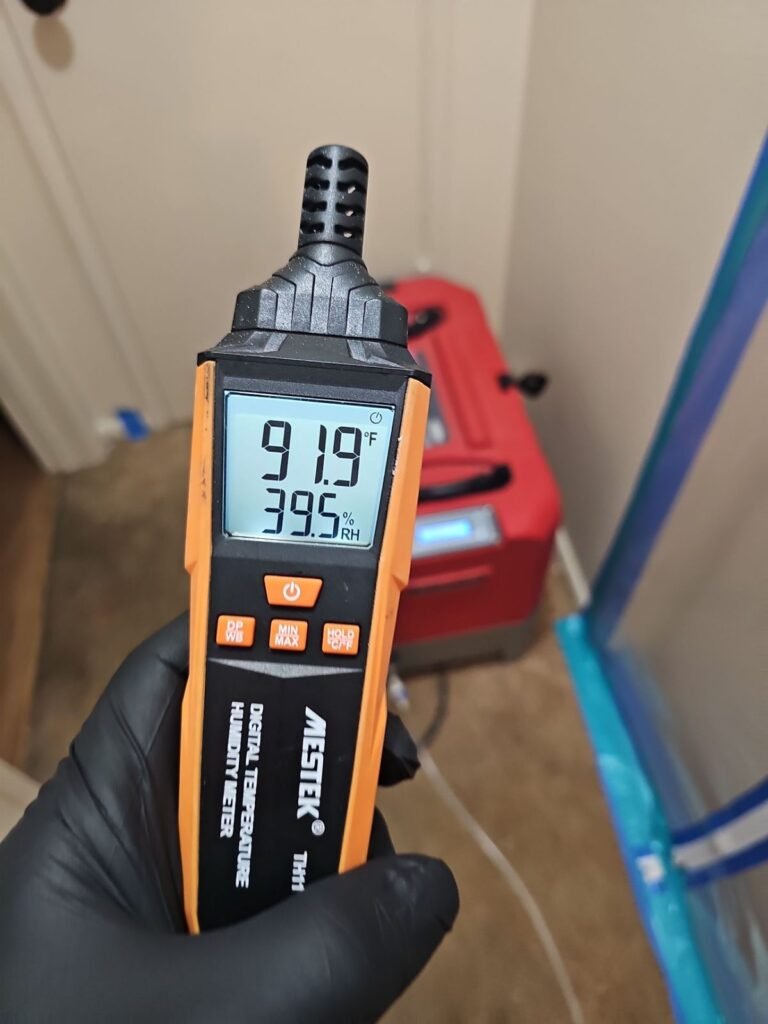
Moisture in every affected room, against every material that holds water, repeated each day the equipment runs. Photographs before anything is moved, then again as material comes out. A log of what dried, what did not, and how long the machines ran.
And a scope of work, the itemized list of what came out and what goes back. With it, the estimate reads as a document rather than an opinion. Nobody argues with a meter reading taken on day one.
One line on that list looks like padding until you know why. An older house has to be sampled before anybody demolishes anything. The guide on what gets tested first in a house that age explains why it belongs on the estimate.
What should I read twice before I sign it?
The rebuild contract, and specifically the number written on it.
State law requires a home improvement agreement in writing, carrying the agreed amount in dollars and cents. That amount has to cover the entire cost of the job: profit, labor and materials together.
Any finance charge has to be listed separately. Business and Professions Code 7159.5. A rebuild sold to you by the hour is not a contract here.
The deposit is where the damage usually happens. A down payment cannot exceed ten percent of the contract amount or the flat ceiling the code sets. The smaller of the two applies, and on a real rebuild the flat ceiling binds first.
Then a contractor may neither request nor accept payment beyond the value of work already performed or material already delivered. Anyone who wants a heavy check before a single tool is unloaded has told you how the rest goes.
There is a penalty written specifically for the people who show up after a disaster. Defrauding an owner over repairs for damage caused by a natural disaster carries court-ordered restitution to the victim. A fine comes on top.
If someone knocks offering to run the claim for you, that is a regulated trade with rules attached. A public adjuster cannot solicit while the loss is still in progress.
They cannot solicit between 6 p.m. and 8 a.m., the window the statute closes off. And during the 7 days after the disaster, they cannot solicit at all.
The contract is cancellable within 72 hours. They cannot hand you money to get a signature. Nor can they hold an interest in any construction, demolition or repair company touching the property.
Our own paper is two documents. Mitigation is billed by the hour, and water damage restoration starts at $61 an hour. You will find the full card on the water damage restoration cost page.
The rebuild reaches you as a single written total, settled and signed before the first tool is unloaded. The code allows nothing else.
The house is dry and the claim is still open. Who do I call about the rest?
Us, for the building. Four other things were never ours, and each carries somebody else’s name.
- The claim: your carrier’s adjuster. Paid, denied or trimmed, the pen is theirs. You file, with our readings, photos and room list.
- A beam or a footing that moved: a structural engineer. Replacing what stood there is ours. Past that, our carpenters get a drawing nobody may improvise on.
- The sign-off: the building department that issued the permit. We apply and book the inspection. The signature belongs to whoever the counter sends.
- What a material is: an independent lab. Asbestos, lead and post-cleanup results arrive on paper from whoever pulled the sample. Looking at a ceiling is not a test.
Work the water never touched gets its own contract, off the claim on purpose. The rest is ours.
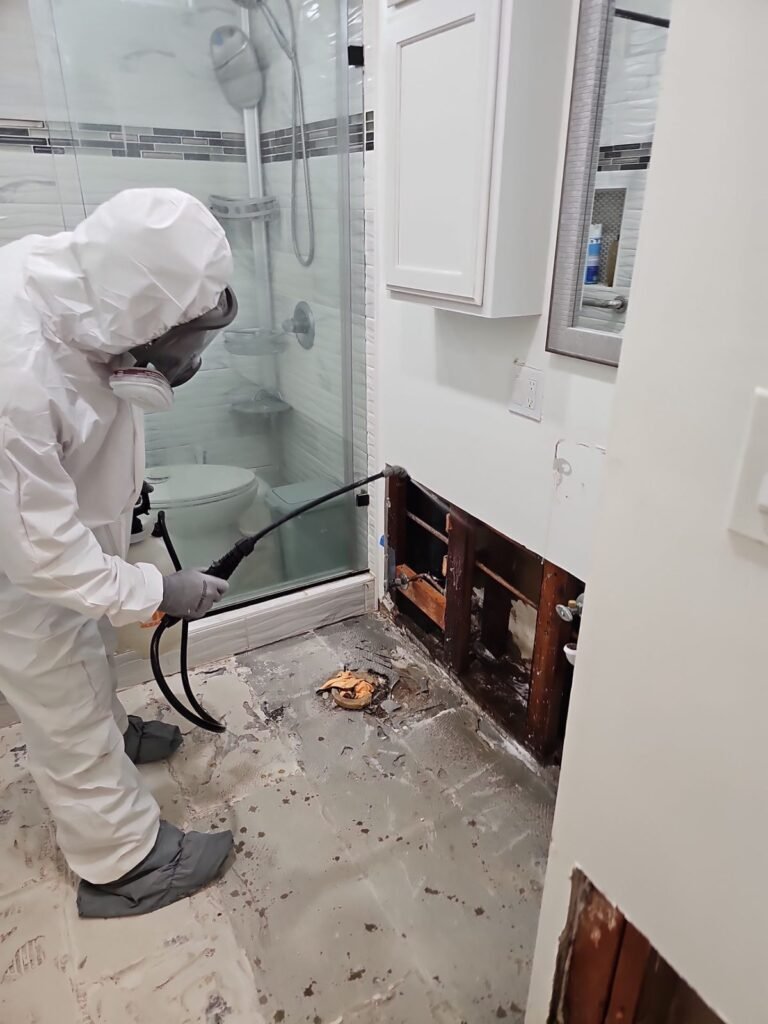
Standing in it now, or sitting at a kitchen table with an estimate you do not trust? Call (805) 427-9039 or write out the whole mess on the contact page.
Every other service sits on the front page of SOS Restoration of Ventura County. Our dispatcher will tell you which of these four the question actually belongs to. The first look costs nothing.
Coast or backcountry, we come ready for it
Water damage
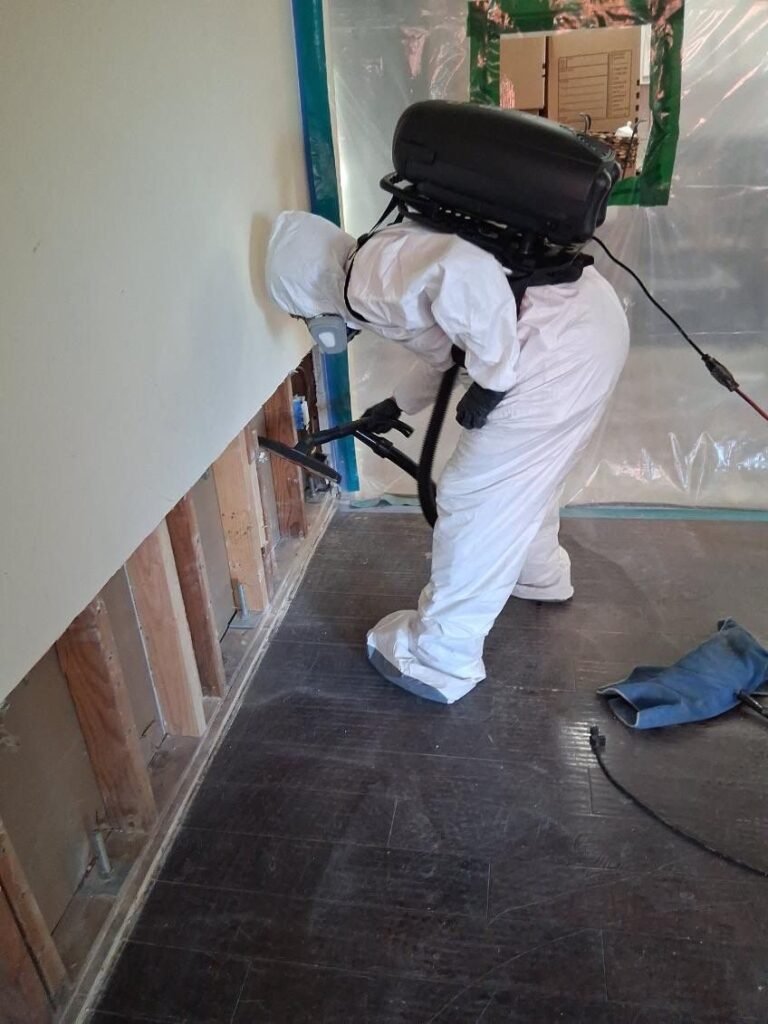
Mold
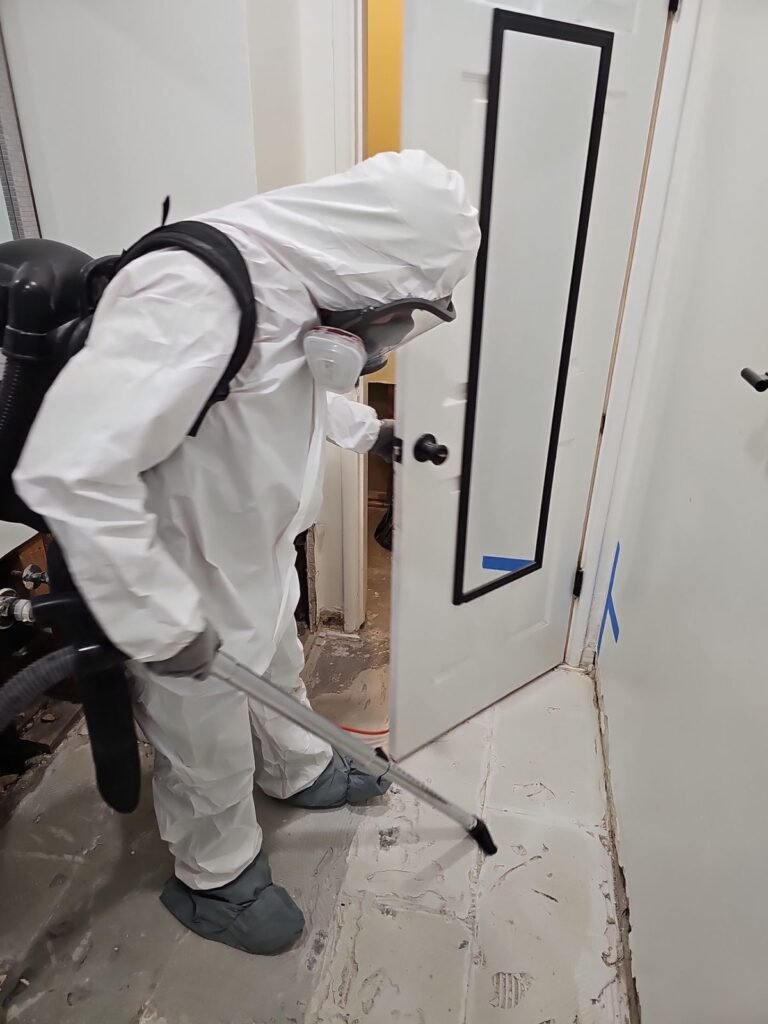
Fire & smoke
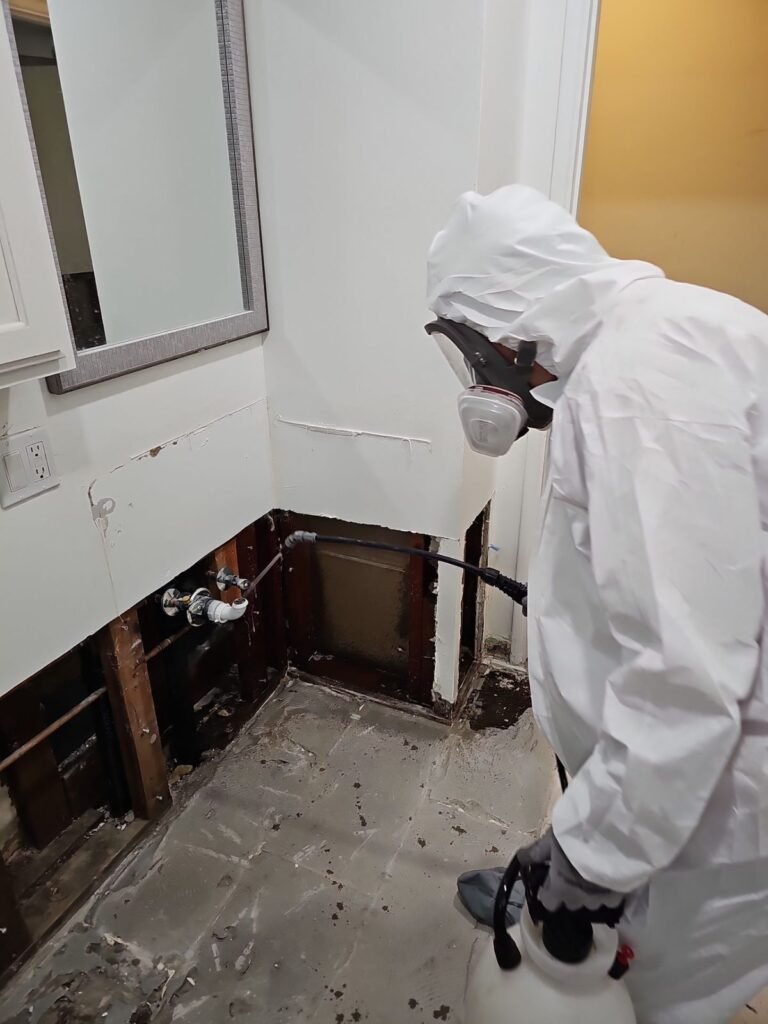
Storm damage
Sewage cleanup
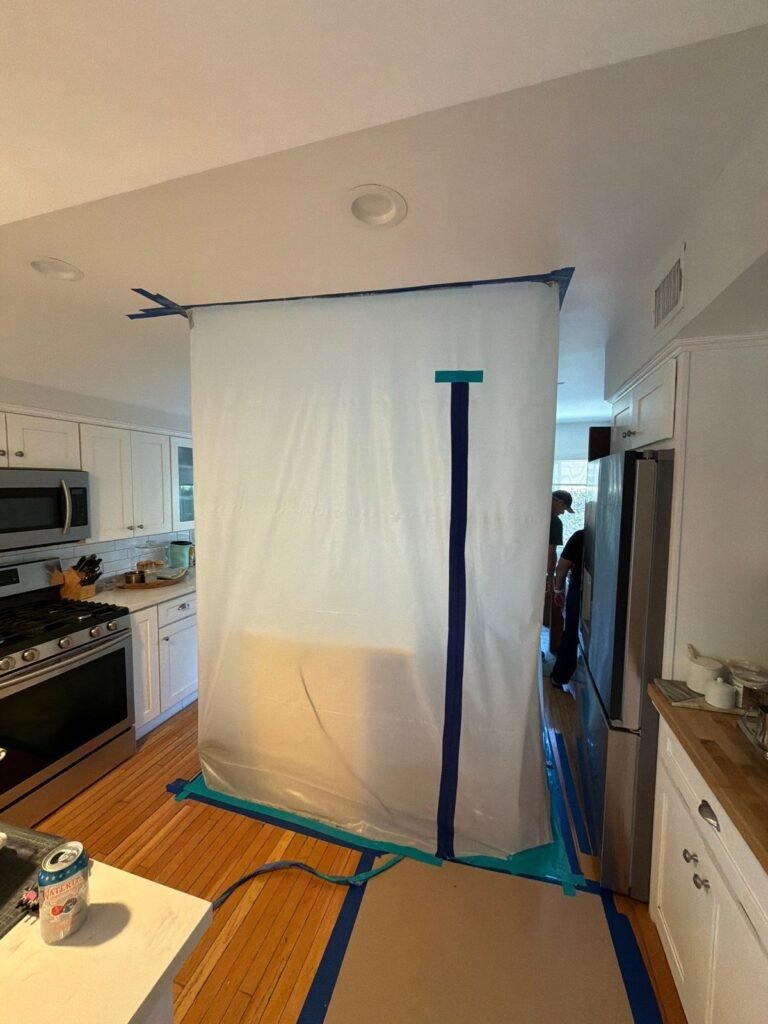
Reconstruction

The cities we drive to for this work
Carriers do not care which city you are in, but the file does. The flood map sits in the paperwork. So do the year the house went up and the name of the agency that issued the permit.
Rather not talk? Write it and we call.
The phone number carries the whole message. What you add only tells us which truck to load and how far it drives.
The homeowners who do well here are the ones holding a folder nobody can argue with.